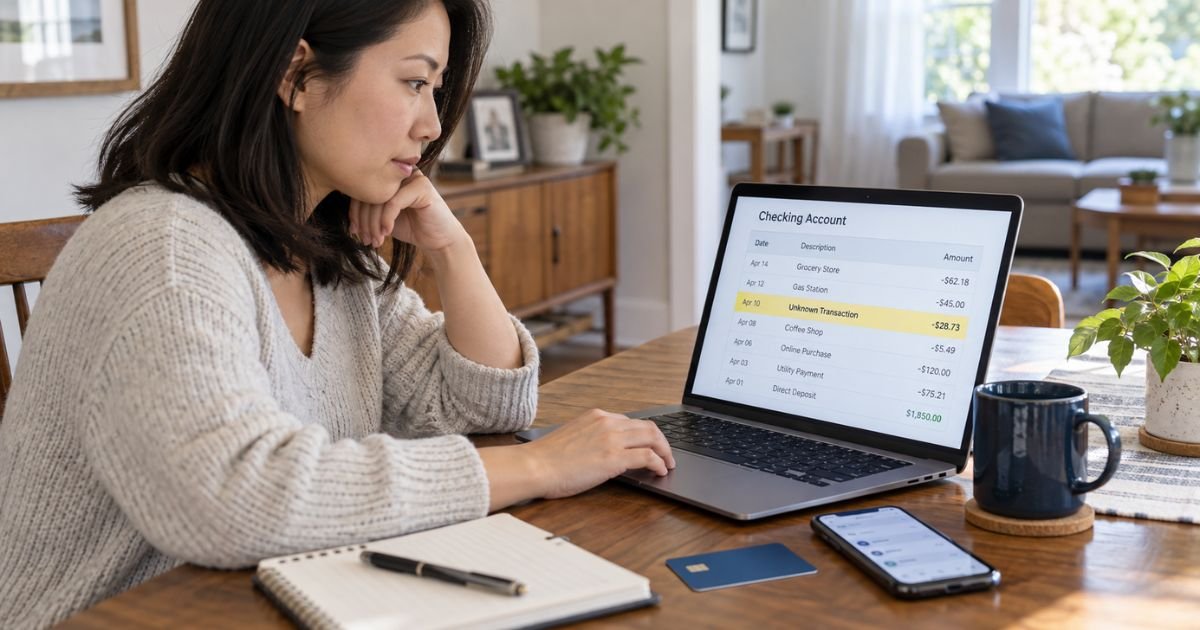
Asking, “What is this charge on my bank statement?” can feel confusing if you don’t recognize the merchant or transaction description.
Many unfamiliar charges turn out to be legitimate purchases, subscriptions, bank fees, or payments listed under unexpected names.
You should still investigate any debit you cannot identify. This guide explains common bank statement charges, how to trace the merchant, and when you should contact your bank.
Table of Contents
What Is This Charge on My Bank Statement?
A charge on bank statement is generally money taken from your checking or savings account. It may come from a debit card purchase, ACH payment, ATM transaction, check, subscription, bank fee, or electronic transfer.
The wording shown next to the transaction is often called a transaction description or merchant descriptor. It may not match the business name you remember seeing at checkout.
| Statement Entry | What It May Mean |
|---|---|
| POS or DEBIT | Debit card purchase |
| ACH | Electronic bank account payment |
| RECURRING | Subscription or repeating payment |
| ATM | Cash withdrawal or ATM-related transaction |
| CHECK | Paper or electronic check |
| PENDING | Transaction not fully posted yet |
| SERVICE FEE | Bank or account fee |
| Unknown merchant name | Legal company, processor, or parent company |
Your bank’s mobile app may show more information than a paper or PDF statement. Tap the transaction before assuming the charge is unauthorized.
Why Does the Merchant Name Look Unfamiliar?
The name on your statement may be the merchant’s legal business name rather than its customer-facing brand.
For example, a restaurant may process payments through its ownership company. An app may bill you under the developer or parent company’s name.
You may also see:
- Abbreviated merchant names
- Payment processor names
- Franchise owner names
- Parent companies
- Store numbers
- Phone numbers
- City or state abbreviations
- Order or transaction numbers
This can make a legitimate transaction difficult to recognize.
Search your email for the transaction amount and purchase date. A receipt may show the brand you remember even when your statement uses another company name.
Pro Tip: Search the exact dollar amount in your email before searching only for the statement name. The amount can often connect an unfamiliar transaction to an online receipt or subscription renewal.
Check Whether It Is an ACH Charge
ACH stands for Automated Clearing House. It is a system used for electronic payments directly to and from bank accounts.
You may see an ACH debit after authorizing a business to withdraw money from your checking account.
Common ACH payments include:
- Utility bills
- Insurance premiums
- Loan payments
- Gym memberships
- Subscription services
- Mortgage payments
- Rent payments
- Online financial services
The descriptor may show the company’s legal name instead of the brand you recognize.
If you previously authorized recurring ACH payments but now want them stopped, you can generally revoke your authorization with the company. You can also notify your bank and ask about stopping future payments.
Stopping the automatic debit does not necessarily cancel a contract or debt. You may still owe the company money through another payment method.
Could It Be a Forgotten Subscription?
Subscriptions are another common source of mystery bank charges.
You may have started a free trial or paid for a service months ago. When the next renewal arrives, the transaction can look unfamiliar.
Check for:
- Streaming subscriptions
- Antivirus software
- Dating services
- Fitness memberships
- Cloud storage
- Gaming services
- AI tools
- News subscriptions
- Meal delivery plans
- Membership programs
Annual subscriptions can be especially difficult to remember because a full year may pass between charges.
Review your email for renewal notices. Also check Apple, Google, PayPal, and other payment accounts connected to your bank or debit card.
Is the Charge Still Pending?
A pending charge has generally been authorized but has not fully settled.
The amount may change before it posts. In some cases, the pending transaction may disappear completely.
Hotels, gas stations, rental-car companies, restaurants, and other businesses commonly use temporary authorization holds.
For example, a gas station may authorize more than the amount of fuel you eventually buy. The final posted transaction should normally replace the temporary hold.
If you recognize the merchant but the amount looks unusual, check again after the transaction posts.
If you do not recognize the merchant at all, you may want to contact your bank sooner.
What About a $0 or Small Charge?
A $0 or small transaction can sometimes be a payment-method verification.
Businesses may verify your card when you:
- Save a debit card online
- Add a card to an app
- Start a trial
- Change subscription details
- Add a card to a digital wallet
The authorization may disappear rather than becoming a final charge.
However, small unfamiliar transactions can also deserve attention. Someone with stolen payment information may sometimes test whether the card or account is active before attempting another transaction.
Contact your bank if you cannot connect the charge to anything you did.
Could It Be a Bank Fee?
Not every debit comes from an outside merchant.
Your bank may charge fees depending on your account and activity.
Possible bank charges include:
- Monthly maintenance fees
- ATM fees
- Overdraft fees
- Stop-payment fees
- Wire transfer fees
- Foreign transaction fees
- Returned-payment fees
- Check fees
The transaction details should generally identify the charge as a bank fee rather than a merchant purchase.
Check your account’s current fee schedule if the wording is unclear. You can also ask your bank what triggered the fee.
How to Identify an Unknown Bank Statement Charge
Start with your bank’s mobile app or website.
Tap the transaction and look for additional merchant details. Your bank may show a full merchant name, location, phone number, category, or payment method.
Then work through these checks:
- Compare the amount with recent purchases.
- Search your email receipts.
- Check recurring subscriptions.
- Review PayPal, Apple, Google, and similar accounts.
- Ask other authorized account users.
- Check ACH authorizations.
- Review ATM withdrawals.
- Search the full merchant descriptor.
Consumer reports on Reddit frequently show that unfamiliar statement names turn out to be subscriptions, shortened merchant names, or purchases made by another authorized household member. These reports are anecdotal, so your bank’s transaction data should carry more weight.
When an Unknown Charge May Be Fraud
You should take the transaction more seriously if there is no reasonable connection to your activity.
Possible warning signs include:
- You have never used the merchant.
- Nobody authorized to use your account recognizes it.
- Several unfamiliar payments appear together.
- Small unknown transactions appear before larger ones.
- Your debit card is missing.
- You receive transaction alerts you did not trigger.
- Cash was withdrawn from an ATM you never used.
If you believe the transaction is unauthorized, contact your bank or credit union promptly.
Use the official banking app or the phone number on the back of your debit card. Do not use contact information from a suspicious text or email.
How to Dispute an Unauthorized Bank Charge
Federal protections can apply to unauthorized electronic fund transfers, including certain debit card purchases, ATM transactions, and automatic bank-account payments. Regulation E contains rules covering error resolution and unauthorized electronic transfers.
Report the problem as soon as possible.
Your bank may ask:
- Which transaction you dispute
- When you first noticed it
- Whether your debit card is missing
- Whether another person has access to your account
- Whether you contacted the merchant
- Whether similar transactions occurred
The CFPB says a bank generally has 10 business days to investigate after you notify it about an unauthorized transaction, although different procedures and extended investigation periods can apply.
Don’t delay simply because the amount is small.
Common Mistakes: Don’t report a legitimate subscription as stolen-card fraud just because you forgot about it. Also don’t ignore an unexplained transaction because it is only a few dollars. Identify the payment first, then describe the problem accurately to your bank.
How to Stop a Recurring Bank Charge
If you recognize the company but no longer want automatic withdrawals, cancel the service through the merchant when appropriate.
You can also revoke permission for future automatic bank debits.
The CFPB recommends notifying both the company and your bank or credit union when you revoke authorization. Your bank may also offer a stop-payment order, although fees can apply.
Keep copies of:
- Cancellation emails
- Revocation notices
- Bank messages
- Support case numbers
- Screenshots
- Payment records
Continue monitoring the account afterward.
How to Prevent Future Mystery Charges
Review your checking account regularly rather than only when your monthly statement arrives.
Transaction alerts can make unfamiliar activity easier to catch quickly.
You can also:
- Keep purchase receipts.
- Review subscriptions every few months.
- Cancel free trials you don’t want.
- Remove saved cards from unused accounts.
- Use strong passwords.
- Enable two-factor authentication.
- Review ACH permissions.
- Keep your debit card secure.
Avoid sharing screenshots that show your full account number or other sensitive information when asking someone to identify a charge.
FAQs: What Is This Charge on My Bank Statement
Q. How can I find out who charged my bank account?
A. Open the transaction in your banking app and check the full merchant details. You can also compare the amount with receipts, subscriptions, ACH payments, and purchases made by other authorized users.
Q. Why does the charge show a company I don’t recognize?
A. The statement may display a legal company name, parent company, franchise owner, or payment processor instead of the brand you remember. The merchant’s contact details or transaction category may help you identify it.
Q. Should I dispute an unknown bank charge immediately?
A. If the transaction appears clearly unauthorized, you should contact your bank promptly. If the merchant is simply unfamiliar, quickly check receipts, subscriptions, and other account users first while continuing to monitor your account.
Q. Can I stop a company from automatically taking money from my account?
A. Generally, yes. You can revoke authorization for future automatic debits and notify your bank or credit union. Stopping the payment does not automatically cancel any separate contract or debt you still owe.
Conclusion
If you’re wondering, “What is this charge on my bank statement?” start by checking the transaction descriptor, amount, date, receipts, subscriptions, ACH authorizations, and other authorized users. Many unknown charges are legitimate transactions displayed under unfamiliar company names.
If the payment still does not make sense, contact your bank promptly. Acting quickly can help you secure your account, stop future withdrawals, and use any dispute rights available for unauthorized transactions.
Disclaimer: This article is for informational purposes only and isn’t financial or legal advice. Bank dispute rules, transaction descriptions, fees, and consumer protections may vary by institution and situation, so verify account-specific questions directly with the company or your bank.
Meet the Author
