
Seeing a balance transfer in credit card activity can feel confusing if you don’t recall signing up for anything new. The line is usually from your card issuer, not a store.
Most of the time the charge is a legitimate move of debt from one account to another. This guide explains what the term means, how fees and 0% offers work, and what to check on your statement.
Table of Contents
What Is a Balance Transfer in Credit Card?
A balance transfer in credit card terms is a transaction that moves an unpaid balance from one card or loan to a different credit card. Your new issuer typically pays the old account. You then owe that amount, plus any transfer fee, on the receiving card.
People usually request a transfer to get a lower interest rate for a limited time. Many offers use a 0% introductory APR on the transferred amount. After that window ends, the card’s regular balance transfer APR generally applies to whatever is left.
The CFPB describes a balance transfer fee as a fee charged to move an outstanding balance to a different credit card. The agency also says a company may charge that fee even on a zero percent rate offer.
How a Balance Transfer Works
You apply for a card with a transfer offer, or you use an offer on a card you already have. After approval, you give the new issuer the old account number and the amount you want to move.
The receiving issuer generally pays the old creditor within several business days to a few weeks. Keep making at least the minimum on the old card until that payoff posts.
You usually cannot move a balance between two cards from the same bank. Rules vary, so confirm with both issuers first.
Most offers also set a deadline after account opening. Miss it, and the transfer may still post at the regular APR instead of the promo rate.
What It Looks Like on Your Statement
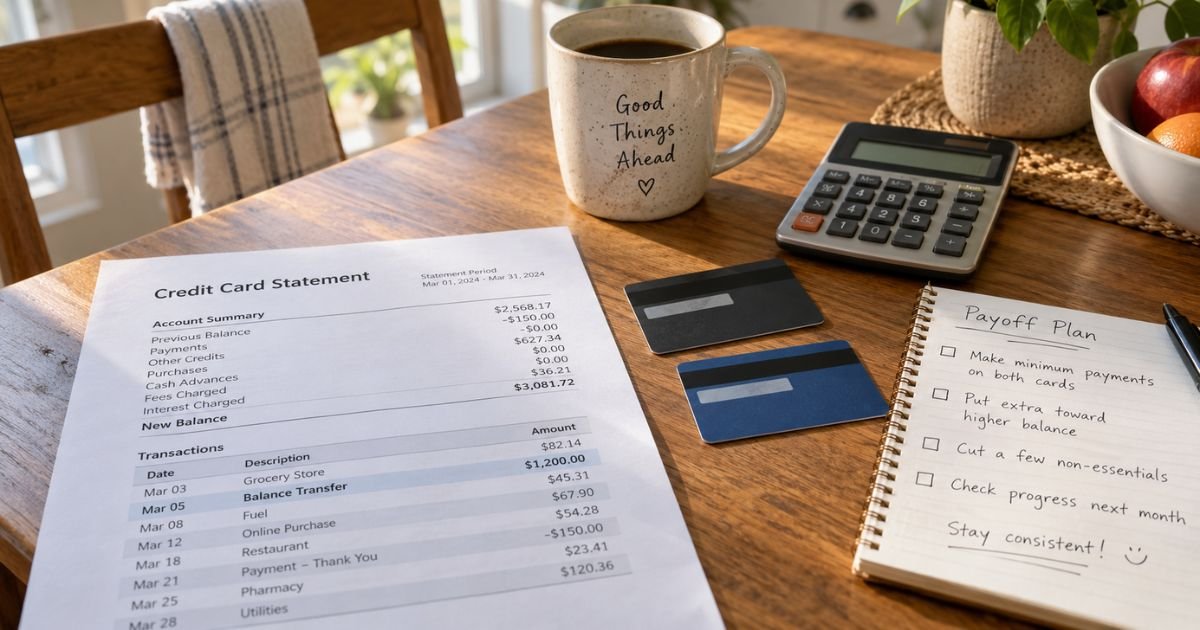
On the receiving card, the line often reads Balance Transfer, Bal Xfer, or a similar issuer label. The fee may appear as a separate Balance Transfer Fee line.
On the old card, you should later see a matching payment or credit. If the two sides do not line up after a few weeks, call both issuers. This is not a store purchase.
Balance Transfer Fees and 0% APR Offers
Issuers typically charge a one-time fee of about 3% to 5% of the amount you move, often with a small dollar minimum. The fee is generally added to the new balance, not paid separately in cash.
A 3% fee on $4,000 is $120, so the new balance would be about $4,120 if nothing else posts. Check the Schumer box. That table must show the fee and the APRs.
A 0% intro APR does not make the move free. The CFPB confirms the fee can still apply. Compare the fee with the interest you would have paid on the old card during the promo window.
Some cards lower the fee for transfers completed in the first 60 to 120 days, then raise it. Terms change, so read the current offer.
How Long the Promotional Rate Lasts
Federal rules require an introductory rate to stay in effect for at least six months, unless you are more than 60 days late on a payment. The issuer must tell you how long the intro rate lasts and what rate applies after that.
Many consumer cards advertise 0% on transfers for about 12 to 21 months. That length is a product choice, not a federal maximum. After the promo ends, leftover transferred balances generally start accruing interest at the regular transfer APR.
A late payment can also end the promo early and may trigger a penalty APR. Make every minimum on time.
If the intro rate is variable, it can still change during the first six months if its index, such as the prime rate, changes.
New Purchases and Your Grace Period
This is the part many people miss. The CFPB says that if you carry a balance month to month, purchases generally accrue interest from the date of the transaction. That is true even when the transferred balance sits at 0%.
If you normally avoid interest by paying in full, that purchase grace period typically applies only if you pay the entire statement, including the transferred amount.
Paying only the minimum keeps the 0% promo, but new purchases may start costing interest right away. The simplest approach is often to stop everyday spending on the transfer card until that balance is gone.
How Payments Get Applied
Your statement may list more than one APR. Purchases, cash advances, and transferred balances can sit in different buckets.
When you pay more than the minimum, the issuer must generally apply the extra amount to the balance with the highest APR first. The issuer usually decides how to apply the minimum itself.
That rule helps if you also have a high-rate purchase balance. Extra payments should hit that higher-rate bucket first.
Pro Tip: Divide the new balance, including the fee, by the months left in the promo. Pay at least that amount each month so a high regular APR does not hit leftover debt.
How to Request a Balance Transfer
Typical steps look like this:
- Read the current offer, fee, promo length, and transfer deadline.
- Confirm the new credit limit can cover the amount plus the fee.
- Request the transfer online, in the app, or by phone using the number on the card.
- Write down the confirmation number and expected posting date.
- Keep paying the old card until the payoff appears.
- Set a payoff plan so the new balance is gone before the promo ends.
Do not wait for the old card to close the debt on its own. Transfers can fail or post late.
Common Mistakes: Closing the old card the same day you request the transfer. Using the new card for everyday purchases while a transferred balance remains. Missing the transfer deadline and losing the 0% rate.
When a Transfer May Help or Hurt
A transfer may help if your current APR is high, you qualify for a long 0% window, and you can pay the balance before that window ends. The one-time fee can then be smaller than months of interest.
A transfer may not help if approval is unlikely, the fee is high, the promo is short, or you keep charging on the same card. A new account typically adds a hard inquiry. Utilization can jump on the new card until you pay it down. You generally still owe the old issuer until its payment posts.
FAQs: Balance Transfer in Credit Card
Q. Is a balance transfer the same as a cash advance?
A. No. A cash advance is usually cash or a cash-like withdrawal from your credit line. It typically has a higher APR and no grace period. A balance transfer moves existing card or loan debt to another card. Some issuers treat convenience checks like cash advances, so read the offer.
Q. Can I transfer a balance if I already have a 0% purchase offer?
A. Sometimes, if the card allows transfers and you still have available credit. Promo lengths for purchases and transfers can differ. Confirm both rates and both end dates in the account terms.
Q. Will a balance transfer hurt my credit score?
A. It can, at least at first. A new application usually creates a hard inquiry. A new account can lower average account age, and utilization may rise on the receiving card. On-time payments and a lower overall balance later may help. Results vary.
Q. What if I do not recognize a balance transfer line?
A. Match the date and amount to a transfer you requested. Check the old card for a matching payment. If you did not request one, call the number on the back of the card. You can also use the CFPB billing-error path for unauthorized or incorrect charges.
Conclusion
A balance transfer in credit card billing is your issuer moving debt from one account to another. It is often a planned tool to cut interest for a limited time, not a random store charge.
Read the fee, the promo end date, and the regular APR before you request the move. Pay on time, avoid new purchases on that card if you cannot pay the full statement, and clear the balance before the intro rate expires.
If the line still does not match anything you asked for, contact the issuer right away.
Disclaimer: This article is for general information only. It is not financial, tax, or legal advice. Credit card terms, fees, and promotional APRs vary by issuer and by offer. Confirm details in your cardholder agreement and with your bank before you transfer a balance or dispute a charge.
Meet the Author
