
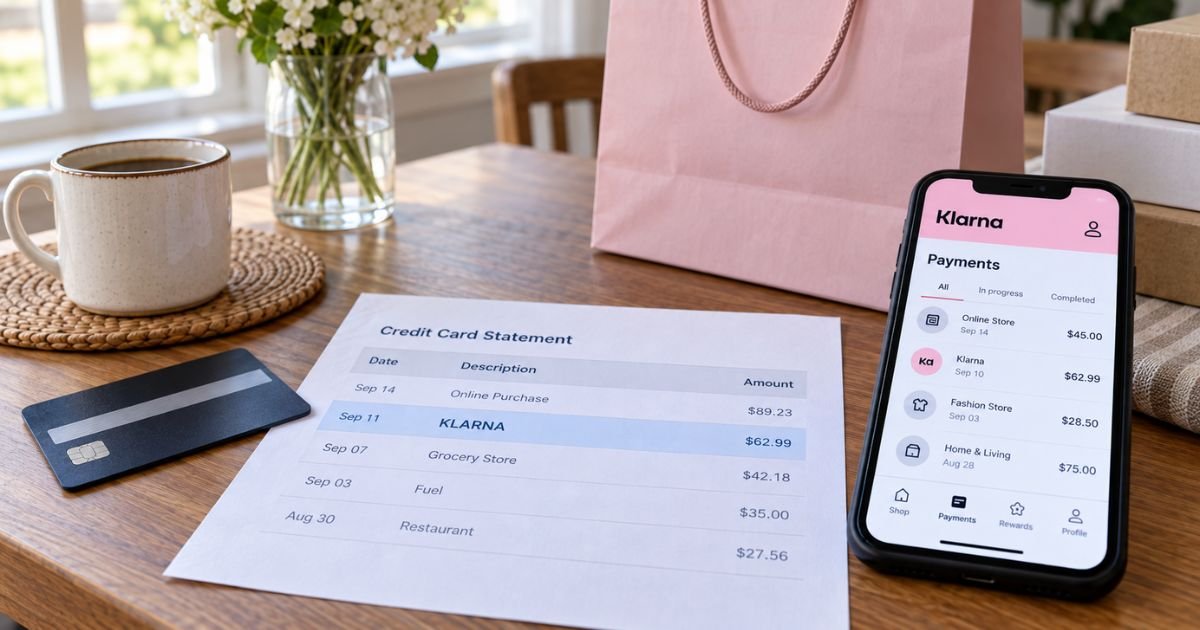
A Klarna charge on a credit card can feel confusing if you don’t recall a store named Klarna. You bought from a retailer. The statement says KLARNA instead.
Unfamiliar Klarna lines are often legitimate checkout payments. Klarna is a real payments and “buy now, pay later” company. This guide explains why the name posts, how Pay in 4 works, and how to match or stop the next pull.
Table of Contents
What is a Klarna charge on a credit card?
A Klarna charge on credit card is typically Klarna collecting for a purchase you made at another store. Klarna sits between you and the retailer. Your issuer often prints Klarna as the merchant, not the shop on the website.
U.S. consumer pages describe several products. Pay in 4 splits a partner-store order into four interest-free payments every two weeks when you pay on time. Pay in Full charges your card today and is not a loan.
Pay later and Pay over time stretch the bill further. Financing and some card products are issued by WebBank. Klarna Inc. is listed at 800 N. High Street, Columbus, Ohio, NMLS #1353190.
Official Pay in Full terms say Klarna will appear as the merchant on your payment-card statement. Card rewards tied to a store category may not apply. That depends on how your issuer codes the purchase.
A Klarna charge on a credit card can also be one installment of Pay in 4. Official U.S. Pay in 4 pages say the first payment comes from your credit card, debit card, or bank when the order ships. The next three are charged automatically every two weeks.
How the charge usually appears
Banks shorten names. You may see a Swedish phone number or “AB” from Klarna Bank AB on international-style lines.
| What you may see | What it often means |
|---|---|
| KLARNA, KLARNA INC, KLARNA.COM, KLARNA US | Common U.S. card wording for a Klarna-collected purchase |
| KLARNA / store name (for example KLARNA/LYST) | Klarna plus the retailer or platform |
| KLARNA WEBBANK or WEBBANK KLARNA | Financing, one-time card, or Klarna Card style product tied to WebBank |
| KLARNA AB and a Stockholm or +46 number | Older or cross-border descriptor style |
| Pending Klarna hold larger than the item | Authorization that official help says can update after the store finishes the order |
Four smaller charges two weeks apart usually mean Pay in 4, not four separate shopping trips. One full-amount line the same day as checkout is often Pay in Full.
Pay in 4, Pay in Full, and other plans
Official Pay in 4 pages say there is no interest and no fee at partner stores when you pay on time. If a collection fails, Klarna says it emails you and tries once more.
If the second try fails, the amount is added to the next payment with a late fee of up to $7.00. Official language says the total of those late fees will never exceed 25% of the order value at purchase.
You may see a larger first installment. Official help says that can happen when Pay in 4 equal payments are not offered, including when the order is above your “purchase power.”
A one-time card in the Klarna app lets you shop at stores that are not partner checkouts. Official help says a service fee can be charged with the first payment on those one-time-card Pay in 4 plans.
An unused one-time card expires in 24 hours if you do not use it. You can also cancel it in Accounts & cards.
Official help says that cancel also drops the related payment plan and service fee. The card authorization hold can take 1 to 7 days to clear, depending on your bank.
Pay over time and the Klarna Card are different. Official Klarna Card help says those purchases go on a monthly statement emailed on the 26th and are auto-withdrawn on the 16th of the following month from a connected bank account.
That help page says checks, debit cards, and credit cards are not accepted as payment for Klarna Card purchases.
Official help on paying an amount due lists U.S. debit cards and ACH. It also says you cannot use credit to pay off purchases made with Klarna’s credit products. Do not assume you can pay a financing balance with another credit card.
Official Pay in 4 FAQ language says Klarna performs a soft credit check. Soft checks generally do not change your score the way a hard inquiry does.
Why you might not remember it
You chose Klarna at checkout to split the bill. The store name never hit the card. A household member may have used the same email login.
Declined Pay in 4 can still leave a pending hold. Official help says that hold is released within 24 hours if the purchase is declined. Your bank may take 1 to 7 business days to show the money as available again.
Taxes, shipping, currency conversion, or a later merchant adjustment can make the card line higher than the item price. Official Klarna Card help lists those reasons and says the store controls the final charge.
Klarna Member or Klarna Plus subscriptions exist on some consumer reviews of fees. Confirm any membership price only in your own app. Do not rely on a third-party dollar figure.
Pro Tip: Open the Klarna app, go to Payments, and match the date and amount. The in-app order names the store even when the card statement does not.
How to match and manage the charge
- Sign in at klarna.com or in the official app.
- Open Payments and find the same amount.
- Read the store name, plan type, and next due date.
- Pay early in the app if you want to stop later automatic pulls on that order.
- For a return or cancel, contact the store first.
Official cancel help says Klarna cannot cancel the store order. The store must confirm. Klarna then cancels the payment plan and refunds what you already paid.
Refunds may go to Klarna balance or back to the original card, depending on your settings. Official help says an open Klarna balance receives refunds automatically.
If the store never cancels in its system, you can still have a plan on a dead order. Official declined-purchase help says to get the store’s cancellation confirmation, then contact Klarna with that proof.
Official U.S. support is chat in the app and phone at (888) 518-2771, listed as 24/7 on klarna.com/us/help. Mailing address on the U.S. contact page is Klarna Inc., 800 N. High St., Ste. 400, Columbus, OH 43215.
Common Mistakes: Disputing only with the card issuer while the store still shows the order as shipped. Ignoring the next three Pay in 4 dates after the first installment. Leaving an unused one-time card authorization to age off without canceling it in the app.
Lookalikes that are not this Klarna line
- Afterpay, Affirm, Zip, or PayPal Pay in 4
- The store charging your card directly after you thought you used Klarna
- A WebBank line with no Klarna wording, which could be another WebBank product
- A Swedish KLARNA AB line from a travel or overseas checkout
- A pending hold that will drop if the order was declined
Open klarna.com yourself. Do not pay a “Klarna agent” who texts a new card number.
If you did not authorize the charge
Change your Klarna password and review linked cards in the app. Chat or call official support. For a Klarna Card purchase, official help describes authorized disputes (wrong amount, missing goods, duplicate) and unauthorized disputes (you did not make the charge).
If the money left a credit card you control, you can also use your issuer’s billing-error process. Federal credit-card rules generally give you 60 days after the statement was sent to dispute in writing. Keep the Klarna order screen and the store receipt.
Klarna is widely used. Trustpilot’s klarna.com page shows a high volume of reviews and a strong overall score. BBB complaint files for Klarna Inc. still include billing and return disputes. Use those as context, not as a verdict on your charge.
FAQs: Klarna Charge on Credit Card
Q. Why does a Klarna charge on a credit card hide the store name?
A. Official Pay in Full terms say Klarna appears as the merchant on the card statement. Pay in 4 collections use the same pattern. The store name lives in the Klarna app under Payments. That split is normal, not proof of fraud by itself.
Q. Will Klarna keep charging my card every two weeks?
A. For Pay in 4, official pages say yes until all four payments are collected, unless you pay early or the store cancels and Klarna updates the plan. Paying one installment does not cancel the rest. Watch the schedule in the app.
Q. Can I stop Klarna from using this credit card?
A. Update or remove the card in the Klarna app and pay remaining balances by another accepted method shown for that product. Official help limits how you can repay Klarna Card and some credit products. Confirm the allowed method on that order before the next due date.
Q. Is a pending Klarna hold a completed charge?
A. Not always. Official help says a declined Pay in 4 hold should release within 24 hours, though your bank may take 1 to 7 business days to show it. A larger hold on a completed plan can also shrink after the store captures the final amount, which official card help says can take up to 14 days.
Conclusion
A Klarna charge on a credit card is typically Klarna collecting for a retailer purchase, often as Pay in 4 or Pay in Full. The statement says Klarna. The store name is in the app.
Match the order, let the merchant cancel returns, and use (888) 518-2771 or in-app chat if the line is not yours. Late Pay in 4 fees are officially capped at $7.00 each and 25% of the original order value in total.
Disclaimer: This article is for general information only. It is not financial, legal, or tax advice. Klarna products, descriptors, late fees, and refund paths vary by plan, store, state, and issuer. Verify account-specific questions with Klarna or your bank before you dispute or change a payment method.
Meet the Author
