
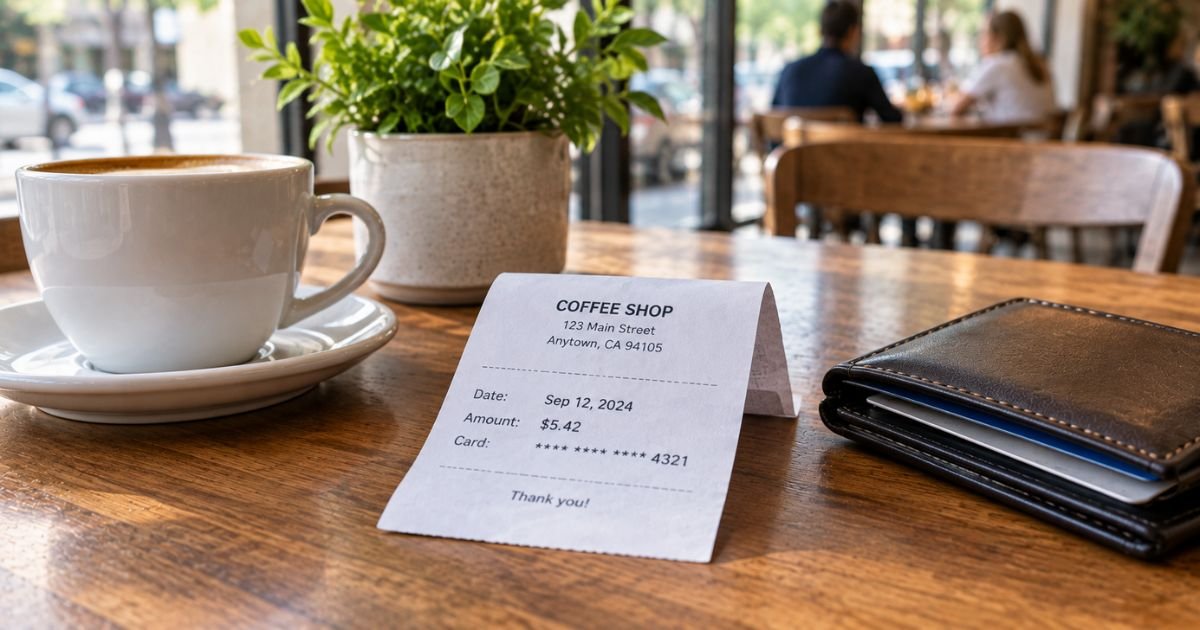
A credit card receipt is the record the merchant gives you at the time of a purchase. It shows the store, the date, the amount, and a truncated card number. It is not your monthly bill, and it is not proof that the charge has posted to your account yet.
If you need to return an item, spot a double charge, or back up a business expense, the receipt has details a statement often leaves out.
This article explains what it includes, how it differs from a statement, what federal law requires on the printed slip, and how long to keep it.
Table of Contents
What Is a Credit Card Receipt?
A credit card receipt is the sales slip created when you pay with a credit card, whether the cashier prints paper or emails a digital copy. It documents that one transaction at that merchant.
Most receipts include:
- Merchant name and, often, the store address or location
- Date and time
- Purchase amount, plus tax and tip if those apply
- Last four or five digits of the card number
- An authorization or approval code
- A short description of the items or a generic category such as “sale”
- A signature or tip line on some restaurant and service receipts
- Separate customer and merchant copies, when paper is used
The receipt is created at the terminal or in the checkout software. Your card issuer later lists the same purchase on your statement, usually with less item detail.
An authorization on the receipt does not always match the final posted amount. Restaurants, gas pumps, and hotels often authorize one figure and settle another later.
Credit Card Receipt vs. Credit Card Statement
People mix these two documents because both mention the same purchase.
The receipt is the merchant’s record of that sale. It can list what you bought, the register time, the clerk or terminal, and the pre-tip total. Stores usually want this slip, or an emailed copy, for a return.
The statement is the issuer’s official summary of the billing cycle. It shows the merchant name, posted date, and amount. It rarely lists every SKU.
Lenders and tax reviewers accept statements as proof of payment. Many stores will not accept a statement as a return receipt.
You need both when something goes wrong. The receipt shows what should have posted. The statement shows what did post.
A $47.19 receipt that appears as $471.90 is a keying error you can document.
What Federal Law Requires on a Printed Receipt
The Fair and Accurate Credit Transactions Act (FACTA) limits what a merchant may print on the electronically printed receipt handed to you at the register.
That customer copy generally may not show:
- More than the last five digits of the card number
- The card’s expiration date
The rule applies to electronically printed receipts given to the cardholder. It does not apply in the same way to every internal merchant record or to a handwritten slip.
If a printed customer receipt shows a nearly full account number or an expiration date, treat it as sensitive. Cover or shred it. You can also tell the merchant the slip does not follow the truncation rules.
Email and text receipts can include more order detail. They should still avoid exposing a full card number.
Customer Copy, Merchant Copy, and Digital Receipts
Customer copy – This is yours. Take it even if you plan to throw it away after you match the statement. Leaving it on the table gives someone the merchant, the time, the amount, and part of the card number.
Merchant copy – The store keeps this for its records, returns, and chargeback responses. On card-present sales it may include a signature. You do not need to leave extra copies of your customer slip with the cashier.
Email, app, and SMS receipts – Online and many in-store checkouts send a digital receipt. Save the message or download the PDF. These copies are easier to search later than a faded thermal slip.
Authorization slip vs. final receipt – A hotel hold or a gas preauthorization is not always the settled charge. Keep the final folio or pump receipt if the first slip only shows an estimate.
At restaurants, review the tip line before you sign. Draw a line through a blank tip field if you are not adding a tip on the slip, or write the total yourself. A blank line can be altered.
Why a Credit Card Receipt Still Matters
Returns and warranties
The store receipt, not the card statement, is what most retailers scan or stamp. Lost the paper? Ask the merchant for a reprint using the date, amount, and last four digits. Many chains can pull a copy from the account you used in their app.
Billing errors and disputes
Federal billing-error rights generally give you 60 days from when the issuer sent the statement that first showed the problem. A receipt helps you show the agreed amount, a duplicate swipe, or a canceled order.
Issuers often ask for the receipt, shipping record, and any messages with the merchant.
Fraud checks
A receipt you never got for a charge you did not make is a clue. A receipt you did get for a charge that later changed is another. Match both to the statement when it arrives.
Business and tax records
The IRS lists credit card receipts and statements as supporting documents for purchases and expenses. A statement proves you paid. A receipt or invoice helps prove what you bought, from whom, and why it was a business cost.
The IRS notes that you may need a combination of documents to cover every element of an expense.
Personal budgets
Item-level receipts explain charges that a short merchant name on the statement will not.
How Long to Keep Credit Card Receipts
There is no single federal rule that says every household must keep every coffee slip for seven years. Match the receipt to the reason you might need it.
Until the charge posts and looks right
Keep routine personal receipts at least until you reconcile that month’s statement. Many people shred them after the statement matches.
Through the return and warranty window
Keep receipts for goods you might take back, plus big-ticket items covered by a warranty or insurance.
For tax deductions and business expenses
Keep supporting records until the IRS limitations period ends for that return. That period is generally three years from the date you filed.
It can be six years if a large amount of income was left off the return, and four years for employment tax records after the tax is due or paid, whichever is later.
Asset purchases should be kept while you own the asset and for the years that follow a sale or depreciation.
A faded thermal slip that only shows a dollar amount may not be enough on its own. Pair it with the statement, an invoice, or a note of the business purpose.
Businesses that accept cards keep merchant copies for chargebacks and sales records. That timeline is separate from your customer copy.
How to Get a Copy If You Lost the Receipt
- Check email, texts, and the merchant’s app first.
- Call or visit the store with the date, approximate time, amount, and last four digits.
- Use the credit card statement to prove the posted amount and merchant name if you only need proof of payment, not a store return.
- Ask the issuer for transaction details. The issuer can describe the charge. It usually cannot reprint the store’s itemized receipt.
Act while the merchant still has the batch in its system. Older in-person sales are harder to rebuild than recent online orders.
How to Store and Dispose of Receipts Safely
Thermal paper fades. Photograph or scan receipts you need for more than a few weeks and name the file with the month and merchant. Do not store a full card number if one appears.
Shred paper receipts that show card digits, your name, or a signature once you no longer need them. Destroy papers with account data so they cannot be read from a trash can. Crop extra card digits before you email or upload a photo.
Common Problems
- The receipt total and the posted charge differ because of a tip, a hotel hold, or a second settlement.
- The statement uses a parent-company name that does not match the storefront.
- A preauthorization drops off and a smaller final charge posts later.
- A digital receipt landed in spam.
When the numbers do not match, start with the merchant. If the statement is still wrong, use the issuer’s dispute process and keep copies of the receipt and your claim.
FAQs: What Is a Credit Card Receipt
Q. Is a credit card receipt the same as an invoice?
A. No. An invoice is the seller’s bill for goods or services, often with payment terms. A credit card receipt shows that you already paid that transaction by card. Some checkout emails attach both.
Q. Can I return an item with only my credit card statement?
A. Usually not. Most stores want the original or reprinted store receipt. The statement can help the merchant find the sale, but it is not the return slip.
Q. Does a signature on the receipt mean I cannot dispute the charge?
A. No. A signature or a chip-and-PIN approval shows the card was used. You can still dispute the wrong amount, a duplicate charge, goods you did not receive, or a charge that does not match what was described.
Q. Should I keep receipts if I pay the card in full every month?
A. Keep them at least until the statement matches. Keep them longer for returns, warranties, and any purchase you might deduct on a tax return.
Conclusion
A credit card receipt is the merchant’s snapshot of one sale. It carries the store name, the amount, the time, and a truncated card number. Your monthly statement later confirms that the issuer posted the charge.
Keep the customer copy until you match it to the statement, and keep it longer when a return, warranty, dispute, or tax record is still in play.
Compare the slip to the bill, store what you need, and shred the rest. That habit is the practical reason a credit card receipt still matters.
Disclaimer: This article is general educational information for U.S. consumers and small-business owners. Return policies, dispute windows, and recordkeeping needs vary by merchant, card issuer, and tax situation. Review unusual charges with your issuer and keep records that support any deduction you claim.
Meet the Author
