The best way to pay off credit cards can feel confusing if you only see a small minimum due each month. That number keeps the account current. It is not a plan to get the balance to zero.
Unfamiliar payoff advice is often just two simple moves: stop adding new charges and pay more than the minimum on a schedule you can keep. This guide compares the usual methods and shows how to pick one.
Table of Contents
Best Way to Pay Off Credit Cards
The best way to pay off credit cards is generally the plan you will follow every month. The CFPB’s money tools present two common orders after you cover every minimum: send extra money to the highest interest rate first, or send extra money to the smallest balance first.
The first order usually costs less interest. The second can feel faster because a card hits zero sooner.
Neither method works if you keep spending on the same cards. New purchases reset the clock. A grace period on new purchases generally applies only when you pay the statement balance in full. If you already carry a balance, new charges typically start accruing interest right away.
Your statement already contains a useful target. Federal rules generally require a box that estimates how long payoff takes if you pay only the minimum, plus a monthly amount that would clear the current balance in about 36 months if you make no new charges.
Use that 36-month figure as a starting payment if it fits your budget.
Start With the Minimums, Then Add a Fixed Extra
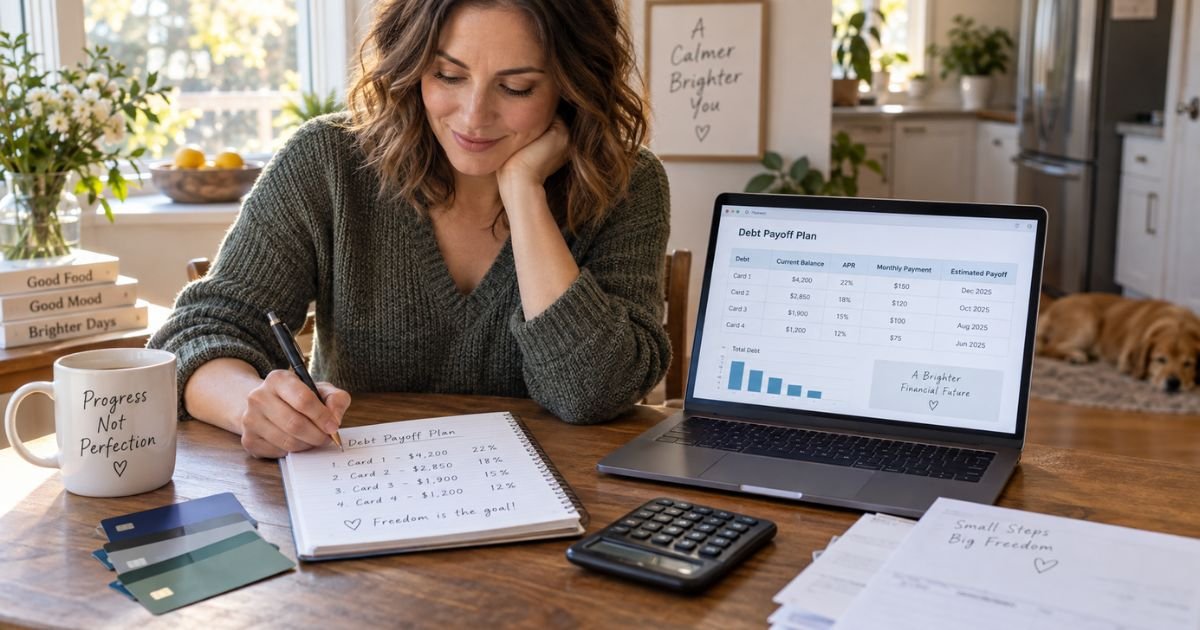
List every card. Write the balance, APR, due date, and minimum. Add those minimums. The leftover amount you can send each month is your extra. Treat that extra as a bill, not a leftover.
Pay every minimum on time. A late payment can add a fee and may trigger a penalty APR. Then send the extra to one target card.
When that card is gone, roll its full payment onto the next target. That rollover is what makes both the avalanche and the snowball grow.
| Method | What you attack first | Typical upside | Typical tradeoff |
|---|---|---|---|
| Avalanche (highest APR first) | The card that costs the most interest | Usually the lowest total interest | The first payoff can take longer |
| Snowball (smallest balance first) | The smallest balance | A quicker closed account | You may pay more interest |
| Fixed payment above the minimum | One card, same dollar amount each month | Simpler than chasing a shrinking minimum | Works only if you do not add new charges |
| Balance transfer or consolidation | Move debt to a lower rate, if you qualify | Can cut interest during a promo or loan term | Fees, approval, and a rate jump when the promo ends |
On one card with more than one APR, extra dollars above the minimum generally go to the highest-rate balance first. That is a federal allocation rule. It does not choose which card you pay extra toward when you have several issuers.
How to Choose Avalanche or Snowball
Choose avalanche if the rate gap is wide and you can wait for the first win. A 27% card costs more each month than a 15% card with the same balance. Clearing the expensive rate first usually saves money if your extra payment stays steady.
Choose snowball if you have several small balances and need a closed account to stay motivated. The CFPB notes the tradeoff in plain terms. Paying small debts first can show progress. Paying high-rate debts later can cost more overall.
You can mix the ideas. Knock out a tiny balance that frees a minimum payment, then switch the extra to the highest APR. The method that keeps you current on every card is better than a perfect spreadsheet you abandon.
Pro Tip: Open the payoff box on this month’s statement. If the 36-month payment fits, automate that amount. If it does not fit, automate the minimum plus the largest extra you can repeat.
Other Tools That Can Lower the Cost
A balance transfer can help if you qualify and if you can finish the balance before the promotional APR ends. Transfers often add a fee, commonly a percentage of the amount moved. The old card is still open unless you close it. Do not use both cards for new spending.
A personal loan can turn several card balances into one fixed payment. Approval and the rate depend on your file. Origination fees can erase some savings. Compare the loan’s total cost with staying on the cards and paying extra.
If you cannot make the minimums, call the issuer now. The CFPB says many companies will discuss a temporary change when you explain what you can pay and when you can resume the regular amount. You do not need to be already late to ask.
Nonprofit credit counseling is another official option. A counselor can review a budget and may set up a debt management plan. You generally make one payment to the agency, which pays the creditors. Ask about fees before you enroll.
The CFPB warns that for-profit debt settlement companies can be risky. They often want you to stop paying cards, which can add late fees, penalty interest, collections, and lawsuits.
Habits That Make Any Method Work
Stop using the cards you are paying down, or leave them at home. Autopay at least the minimum so a missed due date does not wipe out your extra payment. Send the extra as soon as you are paid, not at the end of the month.
Pay more than once a month if that helps you. Extra principal generally reduces the balance that the next cycle’s interest uses. Confirm with your issuer how mid-cycle payments post.
Keep a small cash buffer if you can. Draining every dollar toward cards and then using a card for an emergency puts the balance right back. A modest emergency fund and a payoff plan can run together.
Common Mistakes: Paying only the shrinking minimum. Transferring a balance and then spending on both cards. Closing your only card before you have a plan for cash expenses. Signing up for debt settlement because an ad promised pennies on the dollar.
FAQs: Best Way to Pay Off Credit Cards
Q. Is the avalanche method always the best way to pay off credit cards?
A. It is typically the cheapest order when you can pay extra and you do not add new charges. The best way to pay off credit cards for you is the order you will keep. If a small-balance win keeps you paying, snowball can still get you to zero.
Q. Does paying extra on several cards at once work better?
A. Splitting a small extra across every card usually delays the first payoff. Cover every minimum, then park the extra on one target. After that card is gone, move the whole payment to the next card.
Q. Will paying off credit cards hurt my credit?
A. Paying on time and lowering balances generally helps more than it hurts. Utilization can drop as balances fall. Closing every card at once can shorten your history and cut available credit. Ask your issuer before you close an account you just paid off.
Q. What if I cannot afford even the minimums?
A. Call each issuer right away and say what you can pay. Then consider a nonprofit credit counselor. Avoid companies that tell you to stop talking to creditors or that guarantee a government bailout for card debt. Those are warning signs the CFPB flags.
Conclusion
The best way to pay off credit cards is a repeatable payment that is larger than the minimum, aimed at one card at a time, with no new charges. Use the 36-month amount on your statement if you can.
Pick avalanche to cut interest or snowball to close a small balance first. Call the issuer or a nonprofit counselor if the minimums no longer fit. A plan you keep beats a perfect method you quit.
Disclaimer: This article is for general information only. It is not financial, legal, or tax advice. Payoff time, interest, transfer fees, and hardship options vary by issuer and by your budget. Confirm figures on your statements and with your card company or a qualified counselor before you change accounts.
Meet the Author
