
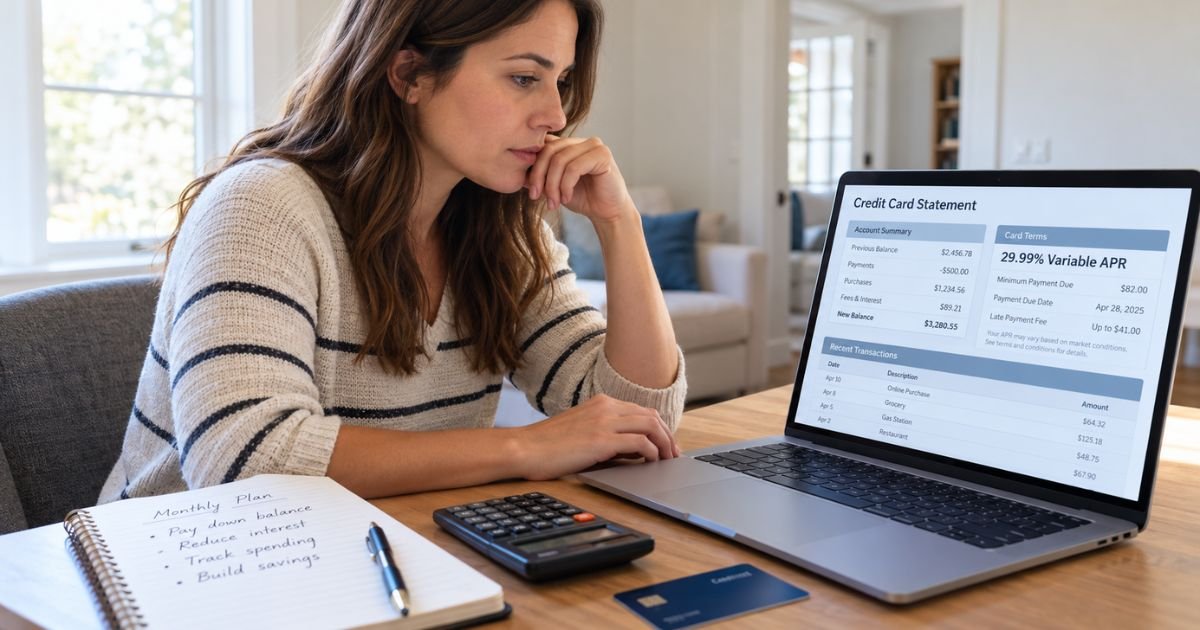
The 29.99% variable APR meaning can seem confusing when you see it on a credit card offer or monthly statement. It generally means your current annual interest rate is 29.99%, but that rate may change over time.
It does not mean your card charges 29.99% every month. You may also pay no purchase interest at all if your card has a grace period and you pay the required balance in full by the due date.
Table of Contents
What Does 29.99% Variable APR Mean?
A 29.99% variable APR generally means your credit card currently has an annual percentage rate of 29.99%. APR is the annualized cost of borrowing money on the card.
The word variable means the rate can change. Your issuer generally ties the APR to an outside interest-rate index, such as the U.S. Prime Rate, and adds a fixed margin.
For example, your card agreement might calculate your rate using an index plus a set percentage. If the underlying index increases, your APR may increase as well.
The same can happen in reverse. If the index falls, a properly indexed variable APR may generally decrease according to the formula in your card agreement.
Does 29.99% APR Mean You Pay 29.99% Every Month?
No. A 29.99% APR is generally an annualized rate, not a monthly interest charge of 29.99%.
A simple way to estimate the monthly cost is to divide 29.99% by 12. That produces an approximate monthly rate of about 2.5%, although actual credit card interest is often calculated daily.
| Balance carried | Rough one-month interest estimate |
|---|---|
| $500 | About $12.50 |
| $1,000 | About $25 |
| $2,500 | About $62.50 |
| $5,000 | About $125 |
These figures are only estimates. Your actual interest may vary based on the number of days in the billing cycle, payments, purchases, daily balances, and your issuer’s calculation method.
How Credit Card Interest at 29.99% Is Calculated
Many credit card issuers generally use a daily periodic rate. They divide your APR by 365 and apply the resulting rate to your balance according to their account terms.
At a 29.99% APR, the daily rate is roughly 0.082%. Interest can therefore accumulate each day that an interest-bearing balance remains on your account.
Your balance may also change throughout the month. New purchases, payments, refunds, and fees can affect the amount used to calculate your interest.
That is why simply multiplying your statement balance by 29.99% usually will not tell you your exact interest charge.
Pro Tip: Check the “Interest Charge Calculation” section of your credit card statement. It generally shows which APR applies to each balance and how much of your balance is subject to that rate.
Do You Pay 29.99% APR If You Pay in Full?
Usually not on ordinary purchases if your card provides a grace period. Most credit cards generally allow you to avoid purchase interest by paying your statement balance in full by the due date.
For example, suppose your statement balance is $1,000. If you pay the full $1,000 by the due date and your grace period applies, you would generally pay no purchase interest despite having a 29.99% APR.
Paying only the minimum is different. The minimum payment may generally keep the account current, but interest can continue accumulating on the remaining balance.
You may also lose your grace period when you carry a balance. In that situation, new purchases may begin accumulating interest according to your card’s terms.
Why Is the APR Called Variable?
A variable APR is generally linked to an index that can move with market interest rates. Credit cards commonly use the Prime Rate as part of this calculation.
The issuer then generally adds a margin. The margin may depend on the specific card, your credit profile when the account was opened, or other factors allowed under the agreement.
For example, a card agreement might describe the purchase APR as the Prime Rate plus a specified margin. The exact formula should appear in your cardholder agreement.
When the underlying index changes, your variable APR may change without the issuer choosing a completely new rate for your account. Federal credit card rules generally require issuers to disclose that the APR is variable and explain which index or formula determines it.
Can a 29.99% Variable APR Go Higher?
Yes, it may. The 29.99% figure generally describes the rate that applies now, not necessarily the highest possible future rate.
If the index tied to your account increases, the APR may rise according to your agreement. Some agreements may also contain maximum rates or other limitations.
Your APR can potentially change for other reasons as well. Promotional rates may expire, and different rules may apply after serious late payments.
Read the pricing section of your card agreement for the exact formula. Your monthly statement should also show the APR currently applied to each type of balance.
Is 29.99% APR the Same for Every Transaction?
Not necessarily. One credit card can have several APRs at the same time.
You might have one rate for purchases and another for cash advances. Balance transfers and penalty balances may also have different rates.
Common categories include:
- Purchase APR
- Balance transfer APR
- Cash advance APR
- Promotional APR
- Penalty APR
Check which category shows 29.99%. A 29.99% purchase APR affects purchases differently from a 29.99% cash advance APR.
Cash advances are particularly important to check. They generally do not receive the same grace period as normal purchases, so interest may begin accumulating immediately.
Is a 29.99% Variable APR High?
A 29.99% APR is generally a high borrowing cost. Carrying a large balance for several months can therefore make purchases significantly more expensive.
However, the APR may matter much less if you consistently pay your purchase balance in full and maintain your grace period. In that case, you may generally avoid purchase interest altogether.
The APR becomes especially important when you expect to carry a balance. Even small differences in APR can affect the total interest you pay over a long repayment period.
Common Mistakes: Don’t confuse APR with an annual fee. APR is an interest rate applied to borrowing, while an annual fee is a separate dollar charge some card issuers collect for keeping the account open.
What Happens If You Only Make the Minimum Payment?
Paying the minimum generally prevents the payment from being considered missed, assuming it reaches the issuer on time. It does not normally stop interest from accumulating.
At 29.99%, carrying a balance while making small payments can make repayment take considerably longer. A portion of each payment may go toward interest instead of reducing the principal balance.
Your statement generally includes a minimum payment warning. This may show how long repayment could take if you make only minimum payments and make no additional purchases.
Paying more than the minimum generally reduces interest costs. Paying earlier can also help when your issuer calculates interest using daily balances.
How Can You Avoid Paying 29.99% Interest?
The most direct method is generally to pay your statement balance in full by the due date each month. This can preserve the grace period on eligible purchases.
You can also reduce the amount of interest by paying down an existing balance faster. Since many issuers calculate interest daily, reducing your balance sooner may lower future interest charges.
Other options may include:
- Making more than the minimum payment
- Making additional payments during the billing cycle
- Avoiding cash advances
- Limiting new purchases while paying down debt
- Asking your issuer whether a lower APR is available
- Considering an eligible lower-rate balance transfer
Balance transfers can have fees and promotional deadlines, so you should compare the total cost rather than looking only at the advertised APR.
Where Can You Find Your Exact Variable APR?
Your current APR generally appears on your monthly credit card statement. Look for a section labeled Interest Charge Calculation, APR, or similar wording.
Your cardholder agreement provides more detail. It should explain the index used for the variable rate and how the APR may change.
If you recently applied for a card, check the pricing table provided with the offer. You may see wording such as “29.99% variable APR based on your creditworthiness.”
If anything remains unclear, contact the card issuer using the number on the back of your card. Ask which balances are subject to 29.99% and whether you currently have a purchase grace period.
FAQs: 29.99% Variable APR Meaning
Q. What does a 29.99% variable APR mean on a credit card?
A. It generally means your current annualized interest rate is 29.99%, but the rate can change based on an index or formula in your card agreement. It does not mean you are charged 29.99% every month.
Q. How much interest is 29.99% APR on $1,000?
A. A simple monthly estimate is about $25 if you carry a $1,000 balance for a full month. The actual amount may vary because many issuers calculate interest daily and your balance can change during the billing cycle.
Q. Will you pay interest if your APR is 29.99% but you pay in full?
A. Generally, you can avoid purchase interest if your card provides a grace period and you pay the statement balance in full by the due date. Cash advances and some other transactions may follow different rules.
Q. Can a 29.99% variable APR change?
A. Yes. A variable APR may increase or decrease when the index tied to the account changes. Your card agreement generally explains the index, formula, and any applicable limitations.
Conclusion
The 29.99% variable APR meaning is fairly simple: your current annualized borrowing rate is 29.99%, and that rate may change based on the formula in your credit card agreement. It is not a 29.99% monthly charge.
If you pay your eligible purchase balance in full and maintain a grace period, you may generally avoid purchase interest. If you carry a balance, a 29.99% APR can make borrowing expensive, so paying down the balance sooner can usually reduce your interest cost.
Disclaimer: This article is for informational purposes only and is not financial or legal advice. APR calculations, grace periods, and card terms may vary by issuer and account. Verify account-specific questions with your credit card company or bank.
Meet the Author
