An insurance deductible can feel confusing if you mix it up with the premium you pay every month. The two are different parts of the same policy.
This guide explains what a deductible is, how it works on health, auto, and home coverage, and how to choose an amount you can actually pay.
Table of Contents
What Is an Insurance Deductible?
An insurance deductible is the amount you pay out of pocket on a covered loss before the insurer pays its share.
The National Association of Insurance Commissioners (NAIC) glossary calls it the portion of the insured loss paid by the policyholder. You do not buy a separate product called “deductible insurance.” The deductible is a term inside your policy.
HealthCare.gov defines a health deductible as the amount you pay for covered health care services before your plan starts to pay.
With a $2,000 health deductible, you generally pay the first $2,000 of covered care yourself. After that, you usually pay a copay or coinsurance, and the plan pays the rest of the covered amount.
On auto and home policies, the insurer typically subtracts the deductible from what it would otherwise pay on that claim.
If repairs cost $1,800 and your deductible is $500, the insurer generally pays $1,300, up to your limit. Liability coverage for injuries or damage you cause to others usually has no deductible.
The monthly or yearly premium is the price of keeping the policy in force. Premium payments do not count toward the deductible.
How a deductible works in plain terms
Think of the deductible as your first layer of a covered claim. The insurer steps in after that layer, if the loss is covered and approved.
A simple auto example helps. Your collision deductible is $500. A covered crash causes $3,000 of damage to your car. You are generally responsible for $500.
The insurer generally pays $2,500, subject to the car’s value and policy limits. If the repair bill is only $400, you typically pay the whole bill. Filing may not be worth it.
Health plans usually use a yearly deductible. Covered bills add up during the plan year until you hit that number. Property and auto deductibles usually apply each time you file a claim, not once a year.
Florida and Louisiana hurricane rules can work differently. Ask your carrier how a named-storm deductible resets.
Only covered charges count. A bill the policy excludes does not shrink the deductible. Out-of-network care may not count the same way as in-network care.
Deductible vs. premium, copay, coinsurance, and out-of-pocket max
These words get mixed together. They are not the same.
| Term | What you pay | When it applies |
|---|---|---|
| Premium | Regular price of the policy | Whether you use benefits or not |
| Deductible | First slice of a covered claim or plan year | Before the insurer shares most costs |
| Copay | Fixed dollar fee for a service | Often after the deductible, per visit or drug |
| Coinsurance | Your percentage of a covered bill | After the deductible, until the out-of-pocket max |
| Out-of-pocket maximum | Cap on deductibles, copays, and coinsurance for covered in-network care | After you hit it, the plan generally pays 100% of covered in-network benefits for the rest of the year |
HealthCare.gov says Marketplace plans generally pay certain preventive services before you meet the deductible. Many plans also cover some checkups that way. Read your summary of benefits.
The federal out-of-pocket limit for a Marketplace plan is capped. For plan year 2026, HealthCare.gov lists no more than $10,600 for an individual or $21,200 for a family. Premiums and noncovered care do not count toward that cap.
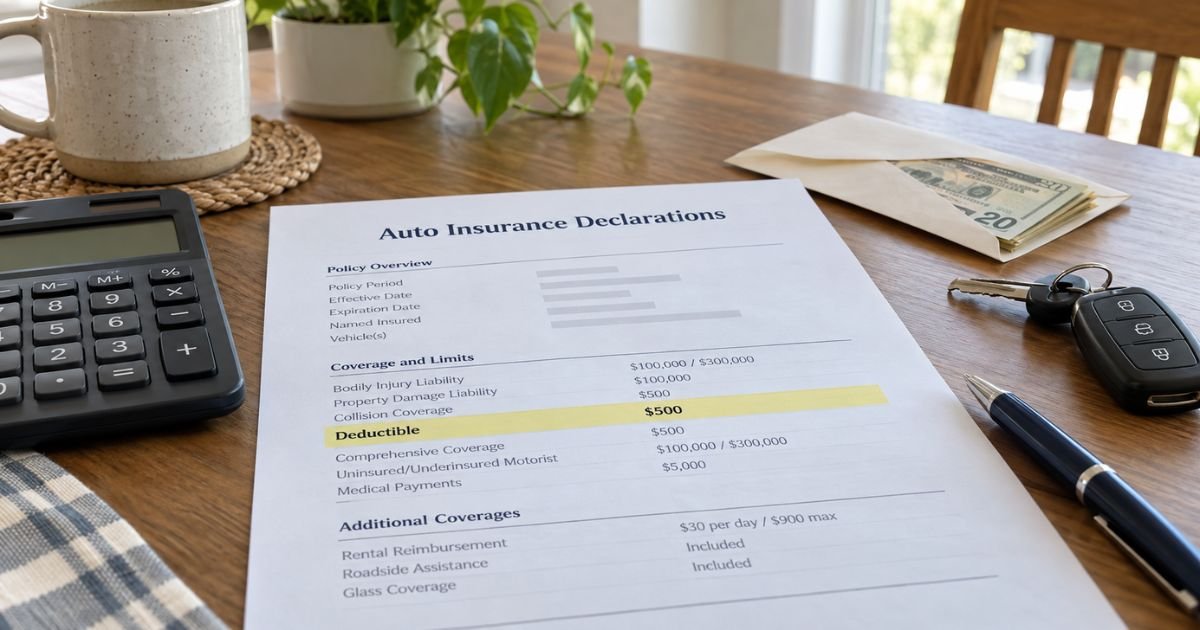
Pro Tip: Open the declarations page of an auto or home policy, or the Summary of Benefits and Coverage for a health plan. The deductible is printed there. Family health plans often list both an individual deductible and a family deductible.
Auto insurance deductibles
Collision pays for damage to your car from a crash with another car or object. Comprehensive pays for theft, vandalism, hail, fire, flood, falling objects, and hitting an animal.
The Insurance Information Institute (III) notes that these coverages are typically sold with a deductible. Collision deductibles commonly fall in a range such as $250 to $1,000. Comprehensive deductibles are often lower, though you can choose more.
Liability coverage pays others when you are at fault. III explains that deductibles generally apply to property damage, not to the liability part of auto or home policies.
Lenders and leasing companies often require collision and comprehensive until the loan is paid. States generally do not require those two coverages. If the car’s value is low, III suggests running the numbers before you keep paying for collision.
III also notes that raising a collision and comprehensive deductible from $200 to $500 could cut those optional coverage costs by about 15% to 30%, and that a $1,000 deductible may save more.
Those figures are industry guidance, not a promise. Savings vary by company and state. Keep enough cash to pay the higher deductible if you crash.
If the other driver is at fault and their insurer pays, you may get your deductible back. That recovery is not guaranteed and can take time.
Home, renters, and disaster deductibles
Home and renters deductibles can be a flat dollar amount, such as $500 or $1,000. Some are a percentage of the dwelling limit.
A 2% deductible on a $300,000 dwelling limit is $6,000 per covered claim. That is a much larger check than a $1,000 flat deductible.
Separate percentage deductibles often apply to hurricanes, named storms, wind, hail, or earthquakes. NAIC consumer material notes that named-storm, wind, hail, and earthquake risks may have their own deductibles.
Earthquake percentages commonly run high relative to the dwelling limit. Read the declarations page. Do not assume one number covers every peril.
Standard homeowners policies typically exclude flood. FEMA and NAIC material note that flood coverage is usually a separate policy. A flood loss does not use your regular home deductible if flood is not covered.
Health insurance deductibles
You generally pay the full allowed amount for most covered care until the yearly deductible is met. Then copays or coinsurance apply until you reach the out-of-pocket maximum.
Some plans use one medical deductible and a separate drug deductible. Family plans may require one person to meet an individual deductible, or the whole family to meet a combined number, depending on the contract.
High-deductible health plans can pair with a health savings account (HSA) if the plan meets IRS rules for that year. Confirm current HSA limits and eligibility with the IRS or your plan. A high deductible only helps if you can pay it when care is needed.
Cash prices paid outside the plan, such as some discount-card pharmacy fills, generally do not count toward the plan deductible. NAIC discussion of those programs makes that point. Run the claim through the plan if you want the dollars to count.
How to choose a deductible you can live with
A higher deductible usually means a lower premium. A lower deductible usually means a higher premium. NAIC consumer pages say raising the home deductible can reduce the price, but you must be able to pay it after a loss.
Ask yourself four questions.
- How much cash could you pay this month without borrowing?
- How often do you file claims?
- Is a lender requiring collision and comprehensive?
- Does your health plan restart on January 1 or on another date?
Do not pick a $2,000 auto deductible if $500 is all you can spare. Do not pick a tiny health deductible if the extra premium crowds out rent. Keep an emergency fund that at least matches your largest property deductible.
Common Mistakes: Treating the premium as if it already “used up” the deductible. Also, filing a small auto claim that is barely above the deductible. A small payout can still affect future pricing. Ask your agent how a claim may change the next renewal.
If a claim or bill does not look right
Start with the policy, not a viral post. Ask the insurer how the deductible was applied. For health bills, ask the plan and the provider for an itemized explanation of benefits.
State insurance departments handle many consumer complaints about claims. The NAIC consumer site can point you to your state regulator. Health plan appeals follow the process in your plan documents and, for many plans, federal internal and external review rules.
This article cannot decide a claim. Coverage always depends on your contract and the facts of the loss.
FAQs: What Is an Insurance Deductible
Q. What is an insurance deductible in simple terms?
A. It is the amount you pay first on a covered claim or, for most health plans, during the plan year. After that, the insurer pays its share of covered costs, up to the policy limits. It is not a separate insurance product.
Q. Does a higher deductible always save money?
A. It often lowers the premium. You pay more if a claim happens. Choose an amount you can pay in cash. Compare the yearly premium savings with the extra risk.
Q. Do I pay a deductible for liability claims?
A. Usually no. III notes that deductibles generally apply to damage to your own property, not to liability coverage that pays other people. Confirm that on your declarations page.
Q. Is the deductible the most I will pay?
A. No. Health plans also use copays, coinsurance, and an out-of-pocket maximum. Auto and home claims can still leave you with amounts above the limit, excluded damage, or a percentage storm deductible. Read the full policy.
Conclusion
An insurance deductible is the out-of-pocket slice you accept before the insurer pays a covered claim. HealthCare.gov, the NAIC, and the III all describe that same idea.
Match the deductible to cash you actually have. Check the declarations page or summary of benefits so the number is not a surprise after a loss.
Disclaimer: This article is for general information only. It is not insurance, financial, or legal advice. Deductibles, premiums, covered perils, and claim rules vary by policy, state, and insurer. Confirm questions about your coverage with your insurer, agent, or state insurance department.
Meet the Author
