
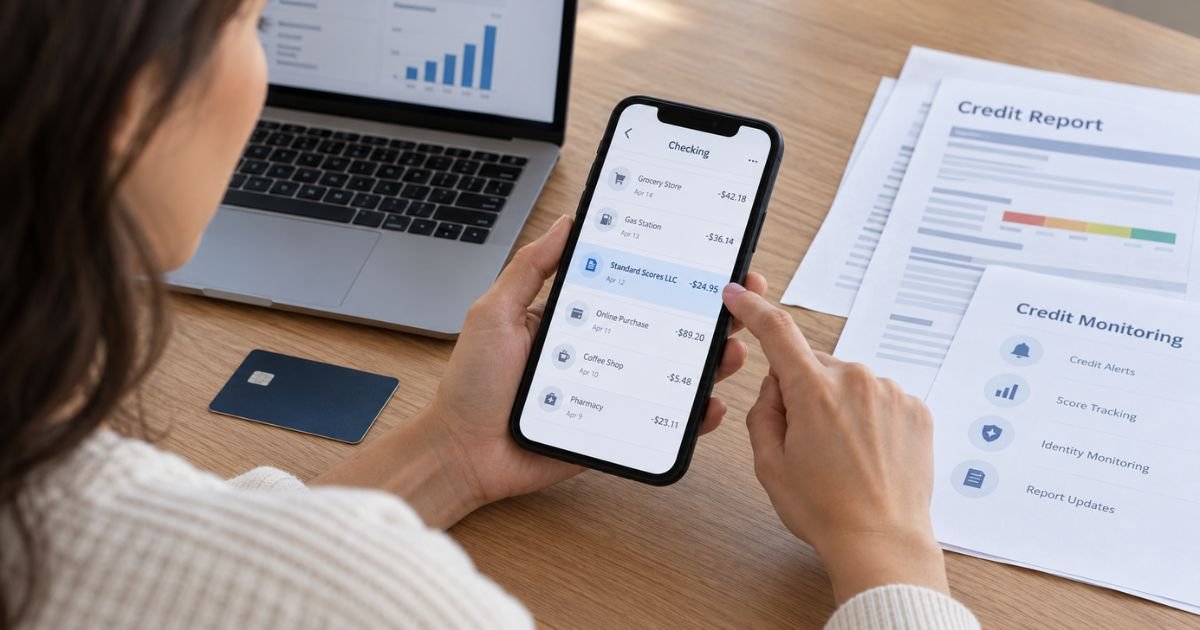
A Standard Scores LLC charge on debit card activity can feel confusing if you don’t recall signing up for anything. The charge may be connected to a credit monitoring subscription, and unfamiliar charges aren’t always the result of stolen card information.
Standard Scores historically offered credit reports, credit scores, monitoring, and credit alerts. This guide explains the charge, the company’s advertised pricing, recent regulatory action, and what you can do if you don’t recognize the payment.
Table of Contents
What Is a Standard Scores LLC Charge on Debit Card?
A Standard Scores LLC debit card charge typically relates to a paid credit monitoring service. The company’s website advertised access to three-bureau credit reports and scores, credit monitoring, alerts, and credit score change notifications.
Standard Scores advertised a $1 seven-day trial followed by a $24.95 monthly subscription. That means you may first notice a small $1 transaction and later see a larger charge.
The company stated that paid subscriptions automatically renewed until canceled. Its terms also allowed charges to the debit card or other payment method provided during enrollment.
However, the company’s situation changed significantly in 2026. Standard Scores is now part of a federal court case involving the Federal Trade Commission.
Why You May See Standard Scores LLC on Your Statement
You may see this merchant name if your debit card information was provided while accessing a credit-related service. In some cases, you may have knowingly visited Standard Scores or agreed to its monitoring service.
In other cases, consumers report that they first encountered the service while trying to deal with:
- A collection account
- A credit report error
- A credit score question
- An Experian, Equifax, or TransUnion issue
- A debt dispute
- A credit repair service
- Another related credit services company
Several consumer reports describe being asked to pay $1 to access or verify credit information. Some later reported seeing a $24.95 Standard Scores LLC transaction.
These reports don’t prove what happened with your particular card. You should compare the transaction with your own calls, emails, and online activity.
What Amount Does Standard Scores LLC Usually Charge?
The company’s website historically displayed two important amounts.
| Charge | Typical explanation |
|---|---|
| $1.00 | Seven-day introductory trial |
| $24.95 | Monthly credit monitoring subscription |
| Repeated $24.95 charges | May indicate recurring billing or attempted collections |
| Different amount | Requires checking your transaction details |
The $24.95 amount is especially important because it matches the monthly price that Standard Scores advertised.
A different amount doesn’t automatically mean the transaction is unrelated. Merchant authorizations, reversals, or other services may produce different entries.
Pro Tip: Search your email and text messages for “Standard Scores,” “credit monitoring,” “credit report,” or “$1 trial.” An enrollment confirmation may explain why the charge appeared.
Is Standard Scores LLC a Real Company?
Standard Scores LLC is a real business entity that provided credit-related services. Its website listed a Henrico, Virginia address and described its products as credit monitoring and credit information services.
However, being a real company doesn’t mean every disputed transaction is automatically authorized. You still need to determine whether you knowingly agreed to the particular payment.
The Better Business Bureau currently gives Standard Scores an F rating. BBB records also show dozens of complaints, including reports involving unexpected subscription charges.
Trustpilot reviews are mixed. A recurring theme in negative reviews is that some consumers say they expected only a small initial charge but later discovered recurring fees.
Reddit discussions contain similar reports. These comments are individual experiences and shouldn’t be treated as proof about your transaction.
What Happened to Standard Scores LLC in 2026?
This is important if you’re researching a recent charge.
In August 2026, the Federal Trade Commission filed a federal lawsuit against Standard Scores LLC and several related companies. The FTC alleged deceptive credit repair practices, unlawful advance fees, and recurring charges that consumers did not always knowingly authorize.
The case remains pending. These are allegations, so they should not be treated as a final court judgment on every claim.
On September 4, 2026, a federal court granted a preliminary injunction. The court found that the FTC was likely to succeed on certain claims involving advance fees and allegedly deceptive practices.
A court-appointed receiver now controls the affected companies. The receiver states that operations of Standard Scores and several related businesses have been permanently suspended.
This means information found on older Standard Scores pages may no longer describe services that are actively operating.
Can Standard Scores Still Charge Your Debit Card?
If you see a Standard Scores transaction now, first check whether it is a newly posted charge, an older transaction, a delayed settlement, or a recurring payment that was previously authorized.
Because business operations have been suspended, a new transaction deserves closer review. Contact your debit card issuer if you cannot connect it to an earlier transaction or authorization.
Your bank can usually tell you more about:
- The transaction date
- The posting date
- Whether it was recurring
- Whether it was card-based or electronic
- Whether additional attempts were made
- Whether the merchant can make future charges
Don’t assume that replacing your card is always necessary. Your bank can tell you whether a merchant block, stop payment, card replacement, or dispute is appropriate.
How to Check Whether You Authorized the Charge
Start by reviewing what happened before the transaction appeared.
Think back to whether you recently called a company about a collection, credit report, debt, or credit score. You may also have clicked a search result while looking for a credit bureau’s customer service number.
Then check:
- Your email inbox
- Spam and junk folders
- Text messages
- Browser history
- Debit card alerts
- Credit monitoring accounts
- Previous $1 transactions
- Recent calls to credit-related companies
Look closely for a $1 debit card charge several days before the $24.95 payment. That pattern may match the former Standard Scores trial structure.
Common Mistakes: Don’t assume that recognizing the $1 charge means you also knowingly authorized recurring billing. Review the enrollment information and any confirmation you received before deciding how to handle the transaction.
How to Stop a Standard Scores LLC Charge
Standard Scores’ older terms said customers could cancel through their account or by contacting customer service. Its website still lists 888-698-7936.
However, the company’s operations are now suspended under a court-appointed receiver. The old customer service process may therefore not work the same way it previously did.
If the charge is still hitting your debit card, contacting your bank is generally the most practical step. Tell the bank whether you recognize the merchant and whether you believe you agreed to recurring payments.
You can ask whether the bank can:
- Block additional merchant charges
- Cancel a recurring debit authorization
- Dispute the transaction
- Replace your debit card if necessary
- Investigate other attempted charges
Keep any cancellation emails, screenshots, transaction records, and bank case numbers.
Can You Get a Refund From Standard Scores?
Standard Scores’ older refund policy stated that customers could request cancellation within seven days of transferring funds and potentially receive a refund.
That policy should not be confused with the company’s current situation.
The court-appointed receiver currently states that refunds for fees previously paid to the affected Credit Glory entities, including Standard Scores, are not available through the receivership at this time. Any future consumer refund process may depend on the outcome of the FTC case and whether sufficient funds become available.
If you believe a debit card charge was unauthorized, you can still contact your bank about its dispute process. Your rights and deadlines may vary based on the transaction and how quickly you report it.
How to Dispute an Unauthorized Standard Scores Charge
Call the number on the back of your debit card or use your bank’s secure app.
Tell the bank that you want to review a Standard Scores LLC transaction. Avoid simply saying that you forgot the purchase if you believe you never authorized recurring billing.
Give your bank:
- The transaction amount
- The posting date
- Any earlier $1 charge
- Cancellation records
- Emails or text messages
- Details about what you believed you were purchasing
Debit card disputes can have time limits. Reporting a suspicious transaction promptly generally gives your bank more time to investigate and may help protect your account.
If your card details may have been exposed, ask whether your debit card should be replaced.
FAQs: Standard Scores LLC Charge on Debit Card
Q. Why did Standard Scores LLC charge me $24.95?
A. Standard Scores historically advertised a $24.95 monthly credit monitoring subscription after a seven-day $1 introductory trial. Check whether you previously provided your card information while accessing credit information or another related service.
Q. Is Standard Scores LLC still operating?
A. Standard Scores operations are currently suspended under a federal court receivership. A preliminary injunction was issued in September 2026 as part of an ongoing FTC case involving Standard Scores and related businesses.
Q. What if I only agreed to a $1 charge?
A. Review any enrollment confirmation to see whether the $1 payment was tied to a recurring subscription. If you believe you never authorized the $24.95 payment, contact your bank and explain exactly what you agreed to.
Q. How do I stop Standard Scores from charging my debit card?
A. Contact your debit card issuer if charges are continuing, especially because Standard Scores’ business operations are suspended. Your bank may be able to block the merchant, stop recurring transactions, dispute a payment, or replace your card.
Conclusion
A Standard Scores LLC charge on debit card activity typically relates to the company’s former credit monitoring subscription. Its advertised pricing included a $1 seven-day trial followed by recurring payments of $24.95 per month.
The company is now under a court-appointed receivership, and its operations have been suspended during an ongoing FTC case. If you don’t recognize the transaction or believe you never agreed to recurring billing, review your records and contact your bank promptly.
Disclaimer: This article is for informational purposes only and isn’t financial or legal advice. Bank dispute rules, refund options, and consumer protections may vary by issuer, so verify account-specific questions with your bank or the appropriate company representative.
Meet the Author
