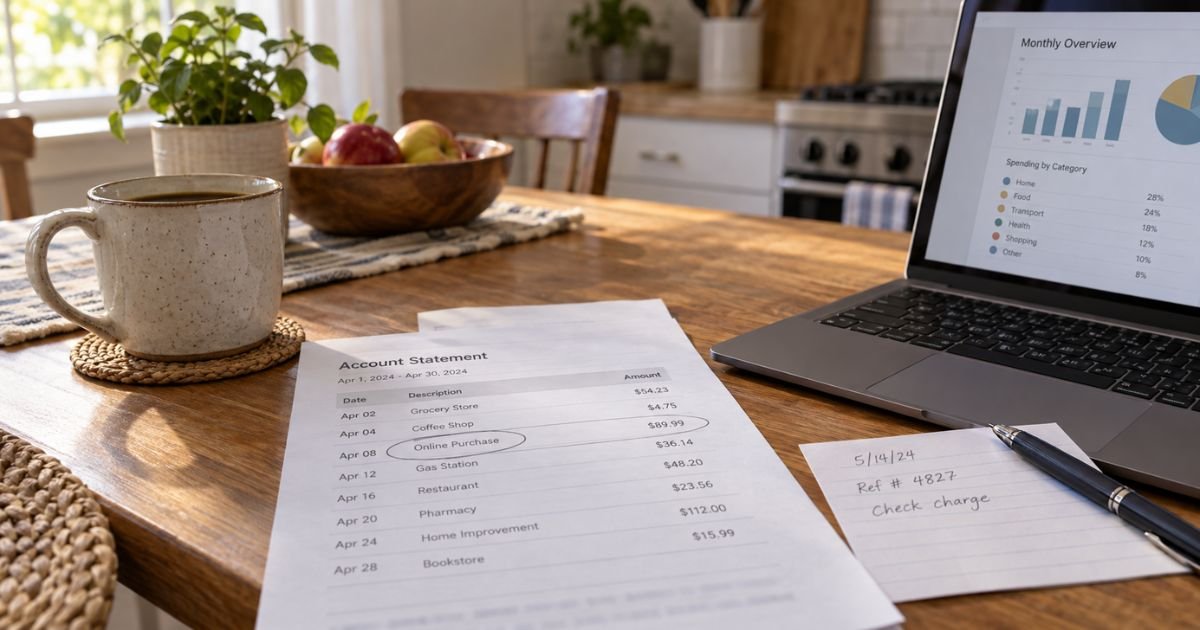
Learning how to dispute a charge on your account can feel confusing if you don’t recall signing up for anything. The line may be a real purchase with an odd name. It may also be a duplicate, a canceled plan, or a charge you never allowed.
This guide shows the usual order. Match the charge first. Try the merchant when the purchase is yours. Use your bank or card issuer when the line is wrong or unauthorized.
Table of Contents
How to dispute a charge on your account
How to dispute a charge on account depends on the account type. Credit cards follow the Fair Credit Billing Act. Debit cards and many bank transfers follow the Electronic Fund Transfer Act. The first phone call looks similar. The deadlines and dollar caps do not.
Start with live activity in the official app, not only last month’s PDF. Pending holds and posted charges need different first steps. A pending store hold is usually the merchant’s to void. A posted charge is what you can formally dispute.
Do not pay a mystery line “just to be safe” and then forget it. You can still dispute a charge you already paid. The Consumer Financial Protection Bureau notes you probably will not see the money back until the company decides you were right.
Step 1: Confirm what the charge actually is
Read the full descriptor. Processors often print a legal name, a city, or a short code instead of the storefront you remember.
Match the date and amount to:
- Email receipts and app-store history
- Gas, hotel, or rental holds that later change
- Household users or authorized users
- Subscriptions and free trials
- Payments you made to the account itself
A weird name is not automatically fraud. A charge you did not allow still needs a fast report. If the card is missing, lock it before you finish researching.
Pro Tip: Screenshot the line, the pending view, and any receipt. Write the date and time of your first call. That small file saves you from repeating the story later.
Step 2: Contact the merchant when the purchase is yours
Call or message the seller first for wrong amounts, duplicate swipes, missing refunds, and goods that did not match the order. The FTC says to contact the seller first when the problem is the quality of an item.
Ask for a refund to the same card or account. Get a case number in writing. Wait a few business days for that credit to post before you open a second claim for the same dollars.
If the merchant ignores you, keep those messages. Your issuer will want proof you tried.
For a pending charge you want canceled, the merchant generally has to void the hold. Banks often will not erase a pending authorization the store still owns.
Step 3: Report it to your bank or card issuer
Call the number on the back of the card or in the official app. Do not use a number from a text or pop-up.
Say whether the problem is:
- Unauthorized use or fraud
- A billing error on a purchase you recognize
- A subscription that billed after you canceled
Many issuers split fraud claims and merchant disputes. Fraud claims usually lock the card and replace the number. Merchant disputes keep the card open and focus on one sale.
Then follow up in writing on a credit card. The CFPB says you should send a written billing-error notice within 60 calendar days after the charge appeared on your statement.
After the issuer gets that notice, it generally has 30 days to confirm receipt unless it already finished the required steps. It then generally has two billing cycles, and no more than 90 days, to resolve the issue.
Send the letter to the billing-inquiries address on the statement, not the payment address. The CFPB’s bill-fix page says to include your name, address, account number, and a clear explanation of what is wrong and why.
The FTC publishes a sample dispute letter you can adapt. Keep copies. Certified mail with a return receipt gives you proof of arrival. If the issuer accepts disputes in the app, save the confirmation screen too.
Credit card vs debit card rules
Use this side-by-side when you are not sure which account posted the charge.
| Topic | Credit card | Debit card or bank EFT |
|---|---|---|
| Main federal rules | Fair Credit Billing Act and Truth in Lending Act | Electronic Fund Transfer Act and Regulation E |
| Written notice window | Generally 60 days after the statement with the error was sent | Error notice rules differ. Report fast, especially if the card is missing |
| Unauthorized-use cap | Generally $50, and often $0 if only the number was stolen | Can rise with delay. Lower caps need quicker notice |
| While the review runs | You generally may withhold the disputed amount | The bank may give a temporary credit on a different clock |
Unauthorized credit-card use is generally capped at $50 for charges before you notify the issuer. The CFPB says you generally owe nothing if someone stole only the account number and not the physical card. Many issuers advertise $0 liability policies. Report anyway so new charges stop.
If you gave a spouse or roommate the card, the issuer may treat those purchases as authorized until you revoke that permission. That is not the same as a stolen card.
What to pay while the dispute is open
Pay every undisputed amount on time. You generally do not have to pay the disputed credit-card amount, or related finance charges, during a valid billing-error review. Skipping the rest of the bill can add a late fee that has nothing to do with the original charge.
You may still see the disputed line on later statements until the case closes. That does not always mean you lost.
A temporary credit can appear during the review. It is a placeholder. If the issuer later sides with the merchant, that credit can come off. The take-back can look like a new charge.
If the company says no
If the issuer finds the bill is correct, it generally must tell you why in writing. It must also tell you how much you owe and when payment is due.
You can write back that you still dispute the amount. Keep paying anything the issuer says is now due if you want to avoid extra fees, and say in writing that payment is not an agreement that the charge was right.
You can submit a complaint to the CFPB at consumerfinance.gov. You can also report fraud problems at ReportFraud.ftc.gov. If the issue looks like identity theft beyond one charge, use IdentityTheft.gov.
Quality problems with goods can follow a second path called claims and defenses. That path has extra limits, including a good-faith try with the seller and, in many cases, a $50 minimum and a same-state or 100-mile rule. Online and phone orders can work differently. Ask the issuer which process it is using.
Common Mistakes: Waiting for the next statement before you write. Calling only the store and missing the 60-day credit-card window. Disputing a pending hold the merchant still has to void. Paying the whole bill, then assuming the dispute filed itself.
FAQs: How to Dispute a Charge on Your Account
Q. How long do I have to dispute a charge on my account?
A. On a credit card, send written notice so it arrives within 60 days after the issuer sent the first statement that showed the charge. Call sooner if you can. Debit-card and ATM problems use different federal clocks, so report those the same day you see them, especially if the card is missing.
Q. Can I dispute a charge on my account in the bank app?
A. Often yes. Many issuers let you tap Dispute or Report fraud in the app. Still save written confirmation. For credit-card billing-error rights, the CFPB still points you to a written notice within 60 days. Ask whether the app filing counts as that notice.
Q. Do I have to contact the merchant first?
A. Contact the merchant first when you authorized the purchase and the problem is a return, a wrong amount, or item quality. Contact the issuer first when you did not allow the charge at all. You can do both. Keep the 60-day credit-card writing deadline while you wait on the store.
Q. What if I already paid the charge I want to dispute?
A. You can still dispute it. The CFPB says you probably will not get the money back until the company decides you were right. Send the same written notice and keep paying any undisputed new activity on time.
Conclusion
How to dispute a charge on your account is a short checklist, not a guessing game. Match the line, try the merchant when the purchase is yours, then tell your issuer and put a credit-card problem in writing within 60 days of the statement that showed it.
Pay the undisputed rest of the bill. Save every confirmation. If the company denies the claim, ask for the written reason and use the CFPB complaint tool when the answer still does not match the facts.
Disclaimer: This article is for general information only. It is not financial or legal advice. Dispute tools, liability caps, and timelines vary by account type and by institution. Confirm account-specific questions with your bank or card issuer, or with official CFPB and FTC pages.
Meet the Author
