
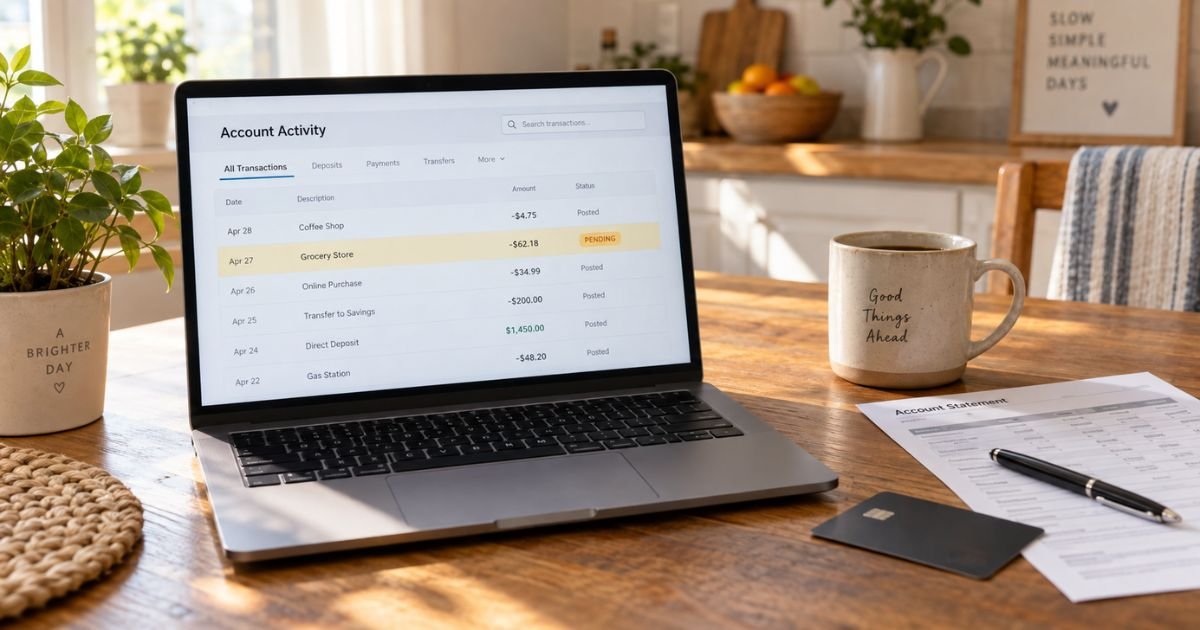
Learning how to cancel a pending transaction can feel confusing if you don’t recall signing up for anything. The line sits in activity but is not on the posted balance yet. It still ties up credit or checking cash.
This guide explains who can drop that hold, when to call the store, and what to do if the charge posts anyway.
Table of Contents
How to cancel a pending transaction
How to cancel a pending transaction starts with one fact. A pending line is usually an authorization hold, not a finished payment.
The merchant asked your bank or card issuer to reserve money. The store has not settled the sale yet. That is why the dollar amount can change, disappear, or turn into a posted charge a few days later.
You generally cannot tap a button in your banking app and force the hold to vanish. Major consumer guides and issuer help pages say the merchant controls a live authorization. The bank can lock the card for fraud. It usually cannot void the store’s hold on its own.
Ask the merchant for a void or an authorization release. Do not ask for a “refund” if the sale has not posted. A refund is a new credit after money moves. A void tries to stop the money from moving.
First, confirm it is still pending
Open live activity in the official app. Pending, processing, or hold means it has not settled. Posted, completed, or “included in your balance” means it already did.
On a credit card, a pending amount lowers available credit. It does not yet add to the statement balance. On a debit card, the hold can reduce available checking even though the cash has not fully left.
Match the merchant name, date, and amount to a receipt, hotel folio, gas pump, or online order. Family members and saved wallets cause many false alarms.
A $1 pending line is often a card-validity check. Those holds typically drop on their own in a few days.
Pro Tip: Screenshot the pending line before you call anyone. If the amount later changes or posts twice, that picture is your proof of what you first saw.
Step 1: Call the merchant for a void
Call, chat, or email the business the same day when you want the sale canceled. Use the number on the receipt or the official website, not a number from a text.
Say the charge is still pending and you need a void or authorization reversal. Give the last four card digits, the date, and the exact amount. Ask for a case number and the name of the person who helped you.
Same-day retail and restaurant mistakes are the easiest voids. Online orders are easier before the warehouse ships. Airlines and ticket sellers follow their own cancel windows. Those windows are not the same as a card-network hold.
If the merchant agrees, the pending line may still sit for several business days. The store sent a cancel message. Your bank has to process it. Watching the app every hour will not speed that up.
Step 2: Call your bank when it is fraud
Skip the store and call the issuer first when you did not allow the purchase. Use the number on the back of the card. Ask to lock or replace the card so the next swipe fails.
The pending fraud line may still post. That sounds backwards. Many issuers can investigate a posted unauthorized charge more cleanly than a hold that has not settled. Report it now anyway so more charges cannot start.
After it posts, send a written billing-error notice on a credit card so it arrives within 60 days after the first statement that showed the charge. Debit-card errors follow Regulation E. Report those fast, especially if the plastic card is missing.
How long a pending transaction usually lasts
Everyday store holds often clear or drop within a few business days. That is a typical range, not a guarantee.
Hotels, rental cars, and some travel merchants use open holds because the final bill is unknown. Those can last longer after checkout. Gas pumps often authorize more than the fill-up, then settle the real amount.
If the merchant never settles, the hold generally expires when the network window ends. You do not always need to do anything for a small check that nobody completes.
| Situation | Who can cancel it | What you typically see |
|---|---|---|
| You want to undo a sale still pending | Merchant void or release | Hold drops in hours to several days |
| You did not allow the charge | Issuer lock, then dispute after it posts | Card replaced; hold may still settle |
| Hotel, rental, or gas estimate | Merchant final bill or release | Amount changes, then posts or drops |
| $0 or $1 card check | Usually no action | Hold disappears on its own |
Do not spend the reserved debit-card cash. If the hold posts after you spent that money, you can overdraw. Credit-card holds do not pull checking cash, but they can decline later purchases.
What to do after the charge posts
A posted sale needs a different tool.
Ask the merchant for a refund to the same card. Get written confirmation. Refunds often take several business days after the store processes them. You may see the original charge and a separate credit.
If the merchant will not help, dispute the posted charge with your issuer. For a credit card, the Consumer Financial Protection Bureau says to call and also send a written notice within 60 days after the charge appeared on your statement.
The issuer generally has 30 days to acknowledge that notice and two billing cycles, no more than 90 days, to resolve it.
You generally may withhold the disputed credit-card amount during a valid review. Pay the rest of the bill on time.
Closing the card does not cancel a pending merchant hold by itself. The store can still submit the sale to the old authorization in some cases. Get the void in writing.
Common Mistakes: Asking the bank to “delete” a hold the merchant still owns. Spending as if a debit hold already vanished. Disputing a $1 pending check that is only a card test. Filing a refund request and a bank dispute for the same dollars on the same day.
FAQs: How to Cancel a Pending Transaction
Q. Can my bank cancel a pending transaction for me?
A. Usually not while it is only a merchant authorization. The store has to void or release the hold. Your bank can lock the card if the charge is unauthorized. After the line posts, the bank can run a dispute.
Q. How fast do I need to cancel a pending transaction?
A. Contact the merchant the same day when you still want the sale stopped. Many voids work only before the store batches the payment. If you wait until it posts, you are asking for a refund or a formal dispute, which takes longer.
Q. Why is a pending transaction still there after the store said it was canceled?
A. The merchant can send a void while your bank still shows the old hold. That gap often lasts several business days. Keep the merchant’s written confirmation. If the amount then posts, send that confirmation to your issuer with a dispute.
Q. Does canceling a pending debit-card transaction free my cash immediately?
A. Not always. Available balance can stay reduced until the hold drops. Ask the merchant for a void, then watch the account. Do not spend the reserved amount until the pending line is gone.
Conclusion
How to cancel a pending transaction is mostly a merchant job. Ask for a void while the line is still pending. Call your issuer first only when the charge is not yours, and lock the card.
If the hold becomes a posted charge, request a refund or send a timely written dispute. Save every case number. That order is slower than a magic “cancel” button, and it is the path that actually works.
Disclaimer: This article is for general information only. It is not financial or legal advice. Hold times, void tools, and dispute rules vary by merchant, card network, and issuer. Confirm account-specific questions with the merchant on the charge or with your bank.
Meet the Author
